
Yes, you can buy a static caravan on finance. Most buyers do. Static caravan finance lets you spread the cost of a holiday home over a fixed term, usually through a personal loan from your bank, hire purchase (HP) from a specialist lender, or a secured loan.
Kingfisher Caravan Park doesn’t offer or arrange finance ourselves, so you’re free to shop around and choose what suits you.
The right option depends on your deposit, your credit history and how long you plan to keep the caravan.
This guide covers how static caravan finance works, where to get it, what each type costs and what to check before you sign. That way you can buy your holiday home on the Lincolnshire coast with confidence.
Static caravan finance at a glance
| Question | Short answer |
|---|---|
| Can you buy a static caravan on finance? | Yes, through personal loans, HP or secured loans |
| Where do you get it? | Your bank or building society, or a specialist caravan lender. You apply directly |
| Does Kingfisher offer finance? | No. You arrange it yourself |
| Typical deposit | At least 10% is common for HP, though it varies. Some loans need no deposit |
| Typical term | Personal loans often run 1–7 years. HP and specialist loans can run up to 10 years, and secured loans longer |
| Is a credit check needed? | Yes, for regulated lending |
| Does rental income count? | Lenders generally judge affordability on your personal income, not rental income |
| Finance term vs licence | Your finance should finish before your pitch licence agreement ends |
What is static caravan finance?
Static caravan finance is a credit agreement that helps you buy a holiday caravan without paying the full price upfront. It isn’t a mortgage. It works more like car finance.
You borrow a set amount, pay it back in monthly instalments and, depending on the product, own the caravan either straight away or once the final payment is made.
Many people also search for “caravan loans”. These are the same thing in practice, and the options below cover them all.
Types of static caravan finance
Personal loan from your bank
For many buyers, a personal loan is the simplest place to start.
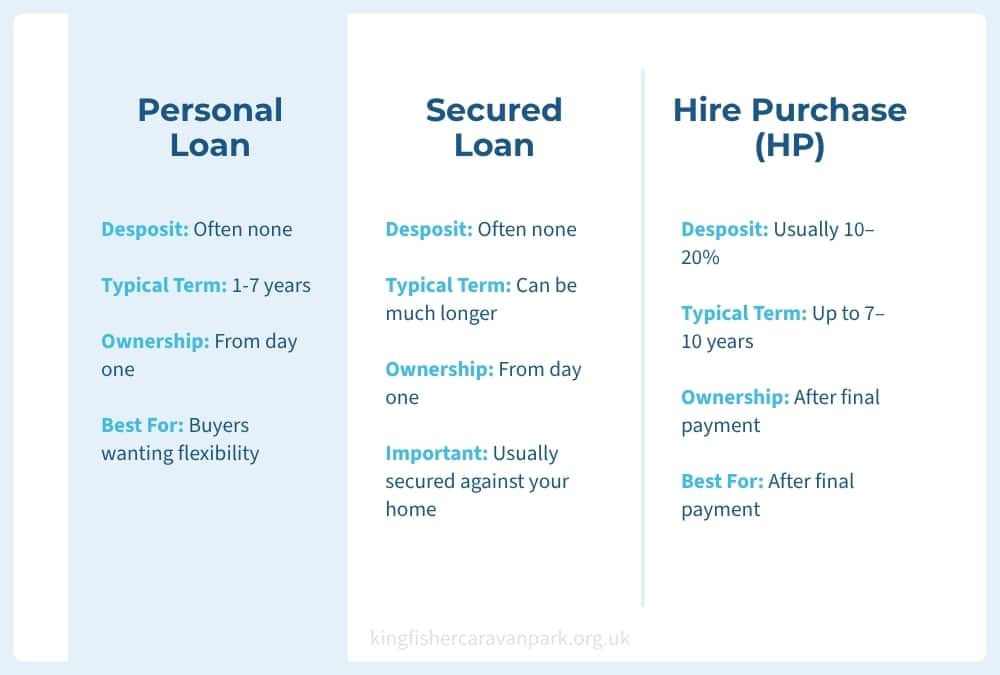
You borrow from your own bank or building society and pay the seller yourself. You own the caravan from day one.
- Deposit: often none
- Term: typically two to seven years
- Good for: buyers with good credit who want flexibility, including anyone buying privately or second-hand
- Check: many banks cap how much you can borrow on a personal loan, so compare the maximum with the caravan’s price. A shorter term also means higher monthly payments.
Your bank already knows your finances, so it’s worth asking them first.
Hire purchase (HP)
HP is offered by specialist caravan lenders. You pay a deposit, then fixed monthly instalments. With HP you only own the caravan once the final payment is made.
- Deposit: usually 10–20%
- Term: commonly up to 7 years, sometimes longer
- Good for: buyers who want fixed payments and longer terms than a personal loan usually allows
- Check: some HP deals are tied to particular dealers or new caravans, so ask before you apply
Secured loan
A secured loan is tied to an asset you own, usually your home. Terms can stretch to 25 years, and some need no deposit.
The risk is serious: if you can’t keep up the repayments, your home could be at risk.
- Good for: larger purchases such as lodges, or buyers who want lower monthly payments
- Think carefully: a caravan loses value over time. A 20-year debt on something that depreciates deserves careful thought.
Comparing your options
| Personal loan | Hire purchase | Secured loan | |
|---|---|---|---|
| Where from | Your bank or lender | Specialist caravan lender | Specialist lender |
| Deposit | Often none | Usually 10–20% | Often none |
| Typical term | 1–7 years | Up to 7–10 years | Can be much longer |
| Ownership | Immediately | After final payment | Immediately |
| Secured against | Your credit record | The caravan | Your home |
| Homeowner needed? | No | Not always | Yes |
Where can you get static caravan finance?
Because Kingfisher doesn’t arrange finance, you’ll apply directly. Your main choices are:
- Your bank or building society. Ask about a personal loan, and check the maximum amount and term.
- A specialist caravan lender. Some offer HP or secured loans, and searching for a “static caravan finance direct lender” will find them. Ask whether they lend on the caravan’s age and for private purchases.
- A broker. Brokers compare lenders for you, but check whether they charge fees.
Whoever you choose, check they’re authorised on the FCA Register, compare the total amount payable and read the full terms.
For free, impartial guidance, visit MoneyHelper.
Can you finance a static caravan over 10 years?
Yes, in some cases. Some specialist lenders offer terms of up to 120 months, depending on the age and tenure of the caravan. Others cap terms at 84 months (7 years).
Bank personal loans usually run for a shorter term.
A longer term lowers your monthly payment, but you pay more interest overall. It also runs into a bigger issue: your finance term should always end before your pitch licence agreement does.
Check how many years are left on your licence before choosing a term.
The age of the caravan (and sometimes the buyer) also affects the maximum term. Older caravans generally get shorter terms.
How much deposit do you need?
Most HP deals ask for 10–20%. A bigger deposit means smaller monthly payments and less interest.
Personal loans often need no deposit, and some secured loans don’t either. But borrowing more means the total cost rises, so a deposit is still worth saving if you can.
Static caravan finance calculator: what will it cost?
A calculator gives you a monthly figure quickly. The example below shows how the term changes the cost.
Illustrative example: £30,000 caravan, £3,000 deposit (10%), £27,000 borrowed at 9% APR.
| Term | Monthly payment | Total interest |
|---|---|---|
| 5 years | about £556 | about £6,350 |
| 7 years | about £430 | about £9,090 |
| 10 years | about £337 | about £13,430 |
These figures are for illustration only and aren’t an offer. Your rate will depend on the lender, the product and your circumstances. A 10-year term is usually only available from specialist lenders.
Stretching from 5 to 10 years saves around £220 a month but adds roughly £7,000 in interest.
When you use any finance calculator, compare the total amount payable, not just the monthly figure.
Static caravan finance eligibility: who can get it?
Lenders usually look at:
- Age and residency: you’ll typically need to be 18 or over and a UK resident
- Affordability: your income and outgoings, plus your other commitments
- Credit history: any missed payments, defaults or CCJs
- The caravan: its age, condition and where it’s sited
- Home ownership: required for secured loans
Many lenders offer a static caravan finance eligibility checker. These often use a soft search, which shouldn’t affect your credit score, so check before you make a full application.
Is it hard to get finance on a static caravan?
Not usually, if your credit is sound and the deal is affordable. Specialist lenders understand holiday homes, and banks will simply assess you as they would for any personal loan.
You’ll have the best chance if you have a stable income, a decent deposit and a caravan that meets the lender’s age rules.
Too many applications in a short time can hurt your chances, so use eligibility checkers first.
Static caravan finance with bad credit or no credit check
Be careful here. Regulated lenders must check affordability, so “no credit check” offers should make you cautious. “Guaranteed” finance isn’t available to everyone either.
If your credit history isn’t perfect:
- Check your credit report first and fix any errors.
- Save a bigger deposit to reduce the lender’s risk.
- Use eligibility checkers to avoid hard searches.
- Ask specialist lenders about their criteria.
- Consider a cheaper caravan so the finance stays comfortably affordable.
No lender can promise approval, and borrowing you can’t afford can leave you in a worse position.
Buying second-hand, privately or off-site
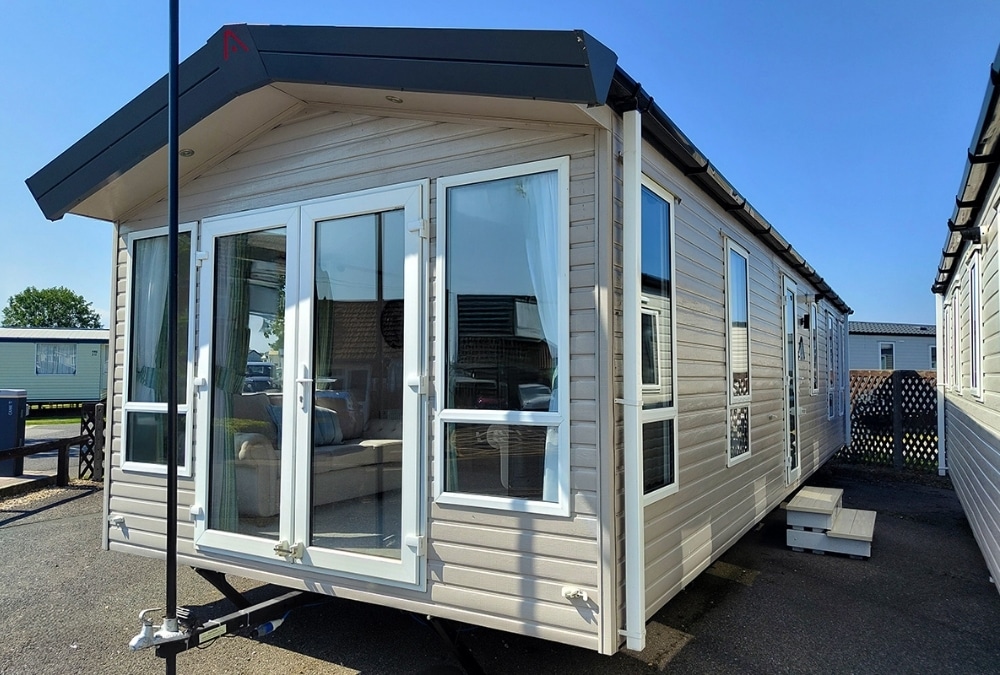
Options narrow when you buy a caravan that isn’t sold new through a dealer.
Some HP deals are tied to dealers, while personal loans and secured loans usually let you buy from anyone. Lenders may also refuse older caravans.
Before you buy any caravan elsewhere, check the park will accept it on its pitches. Many parks have age and condition rules, so read our guide to buying a new or used caravan first.
Hidden costs and rules to check before you sign
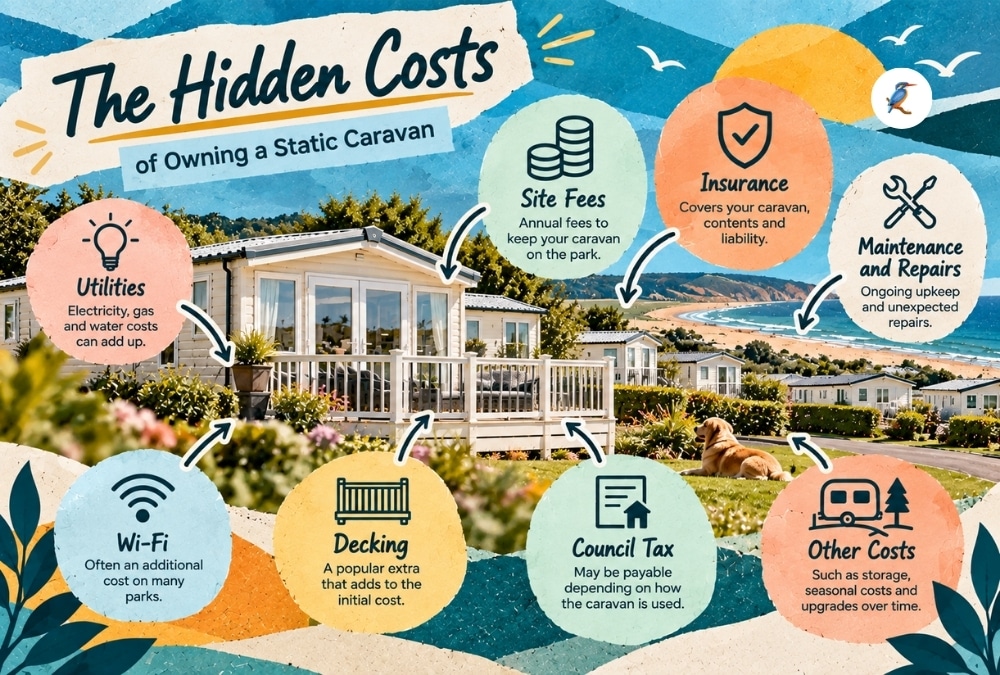
Finance covers the purchase price, but owning a caravan costs more than that. Check these before you commit:
- Licence length: does it outlast your finance term?
- Site fees: these are yearly and usually paid on top of your finance
- Rental income: lenders base affordability on your personal income rather than sub-letting income, so don’t plan to fund repayments that way. See our guide to sub-letting your caravan.
- Living in it: holiday caravans can’t be your main home. Read can you live in a static caravan.
- Depreciation: caravans lose value over time
- Insurance: see static caravan insurance explained
- Early settlement: some agreements charge for paying off early
Our breakdown of the true cost of owning a static caravan shows how these add up.
If you’re buying on a licensed holiday park like ours, it doesn’t affect your purchase or your finance. You can read more in our guide to the legal requirements of owning a caravan.
Buying a static caravan at Kingfisher Caravan Park
Our park in Ingoldmells is a short walk from the beach and close to Skegness.
We don’t arrange finance ourselves, which means you can choose whichever lender, or your own bank, gives you the best deal.
We’re happy to help with the parts we do know. Ask our sales team about your pitch licence length and the caravan age rules, so you can match your finance term to them.
It’s also worth getting an agreement in principle from your lender before you reserve a caravan. Browse our static caravans for sale, or read our first-timer’s guide to buying a static caravan.
Not sure whether ownership is right for you? See the benefits of owning a static caravan.
Static caravan finance FAQs
Can you buy a static caravan on finance?
Yes. Most buyers use a personal loan, hire purchase or a secured loan.
Does Kingfisher Caravan Park offer finance?
No. You’ll arrange finance yourself with your bank or a specialist lender, and our sales team can help with licence and caravan details.
Can I use a bank personal loan to buy a static caravan?
Yes. A personal loan lets you own the caravan from day one and buy from any seller. Check the maximum amount and term your bank offers.
How do I finance a static caravan?
Decide your budget, check your credit, use an eligibility checker, compare the total cost across lenders, then apply. Check the park’s licence length and caravan age rules first.
Can I finance a static caravan over 10 years?
Sometimes. Terms of 7–10 years are available from some specialist lenders, and secured loans can run longer. Your finance should end before your licence does.
Can I get static caravan finance with no deposit?
Yes, sometimes. Personal loans and some secured loans need no deposit. You’ll borrow more and pay more interest overall.
Can I get static caravan finance with bad credit?
Some specialist lenders look beyond your credit score, but approval is never guaranteed. Be wary of any “no credit check” claims.
Can I finance a static caravan I rent out?
Yes, but lenders usually judge you on personal income, not rental income.
Is static caravan finance regulated?
Most consumer credit is regulated by the Financial Conduct Authority (FCA). You can check a lender on the FCA Register, and find free guidance on MoneyHelper.
Ready to buy your holiday home?
Static caravan finance can make ownership far more affordable, if you choose the right product and keep the total cost in view.
Work out your budget, compare offers, and check your licence before you sign.
Ready to look at caravans? Contact our sales team or visit us in Ingoldmells.
This guide is general information, not financial advice. Kingfisher Caravan Park does not offer or arrange finance and isn’t a credit broker. Rates and terms vary by lender, so always check the full terms before you sign.